


It’s been about four months since my initial coverage of Xtract One Technologies. While I didn’t dislike the company overall, I awarded them a mediocre 2.75 stars citing concerns around their float management, vague contracts and overall valuation.
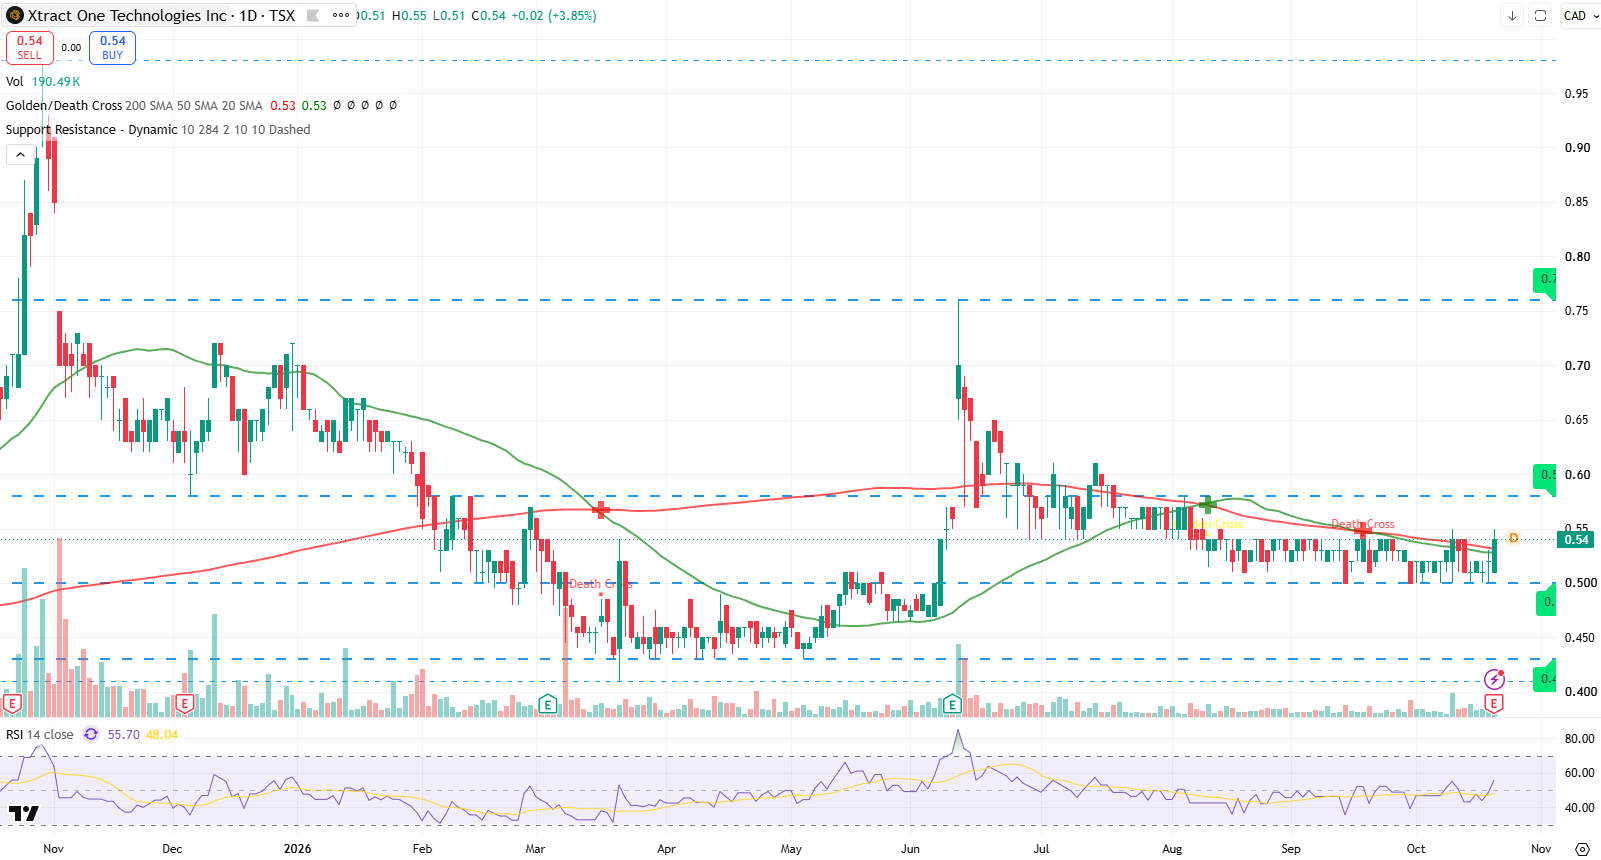
The stock is down 5% since that review and trading around a $140M market cap. I did move them to a watchlist due to improving fundamentals and mentioned I could get interested if the stock entered the 40’s. It never quite got there clinging to 50 cent support for much of the last three months.
You can read what I had to say back at the end of June below.
Xtract One Technologies ($XTRA.TO)

This will be my first look and review of Xtract One in what appears to be some heavy interest out of the Wolf Den discord.
Xtract One released their Q4 and 2026 annuals after the market closed yesterday. Let’s check on their progression, or lack thereof.
The Company:
Xtract One Technologies is a Toronto-based company that develops and commercializes AI-powered weapons detection and threat detection gateway solutions. Their recently updated investor presentation is linked below.

Balance Sheet:
XTRA has an excellent looking balance sheet starting with a current ratio of 6 with deferred revenue removed. That consists of $17.3M in cash, $4.4M of receivables, $4.3M worth of inventory and $2.8M in prepaids against just $4.75M in liabilities due over their next twelve months.
In my last review I noted that the growth of A/R is outpacing revenue growth and that continues after their Q4. In fairness, XTRA’s back half was much stronger than their front half so you would expect to see some of that. Xtract One does not do us any favours by not including an A/R aging report. While not all companies provide one on a quarterly basis, it is highly unusual for a company to not provide one at any point during the year including their annual filings. That gets my antenna up somewhat, particularly when they added a provision of $120k for uncollectable accounts that wasn’t there last quarter. It’s not enough to be a red flag yet, but they could make me feel a lot better about it by providing some proper disclosure.
Inventory rose at just half of their revenue growth improving productivity and turnover, but it’s worth mentioning over $500k in write downs occurred for obsolete inventory over the past two years.
Xtract is debt free and despite a couple of minor concerns, they are very good shape.
Cash Flow:
Last quarter I suggested their operational cash flow was better than it appeared and that played out to be the case in Q4 where extract generated $1.87M in OCF compared to burning $1.1M last year for a $3M improvement on a comparable basis.
Unfortunately, they still burned $3.5M on the year but that is considerably better than $6.5M they went through in 2025 and the $5.4M worth of burn through nine months.
Before anyone spikes the football, it’s notable that the burn rate prior to working capital adjustments was still $500k in Q4, so they are still far from being considered to be a cash flow generator.
The good news is their balance sheet can withstand a prolonged period at these burn levels.
The reason they are in this excellent cash position stems from their raise back in November at 75 cents. That looks extremely opportunistic now with the stock down well over 30% since then.
Xtract utilized approx $400 on asset purchases during the year. Overall their cash position increased by $9M from the end of last year, an improvement of 110%. Thank you opportunistic raise.
Share Capital:
260.1M shares outstanding, 19% dilution over the past twelve months
A whopping 76.6M warrants outstanding. 16.9M are currently ITM with the most recently issued 8.6M well out of it. But another 51M are within seven cents and all expiring with in the next two years.

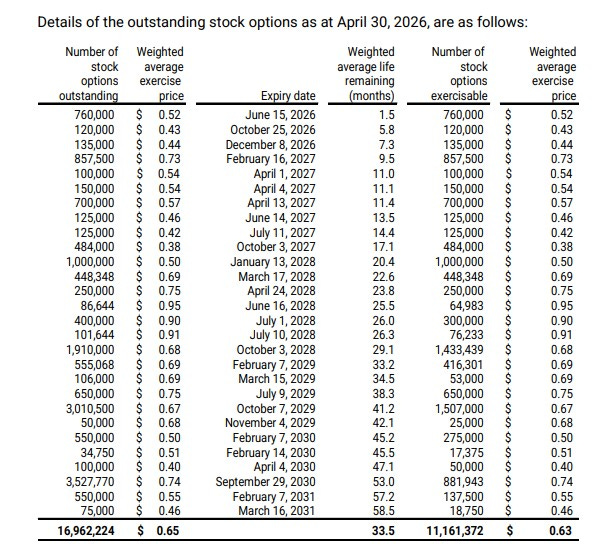
17M options with 5.1M ITM and another 6.1M within a dime.
Very small insider ownership of 0.52% with 0.73% institutional ownership. The largest shareholder is MSG Sports with a 13.5% stake. (per SimplyWallSt)
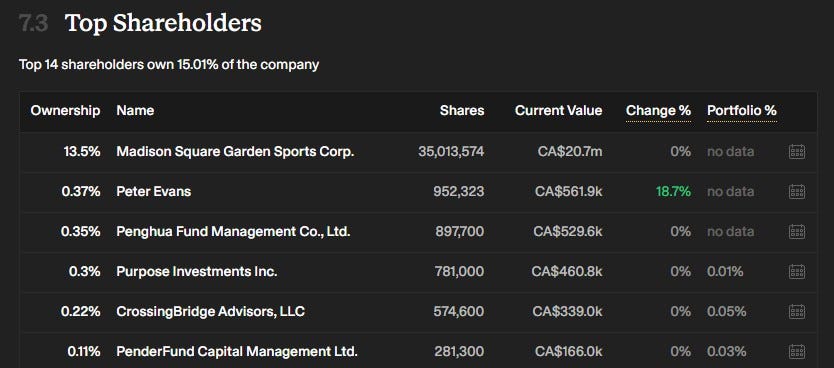
The CEO recently added 1M shares at $0.52.
Income Statement:
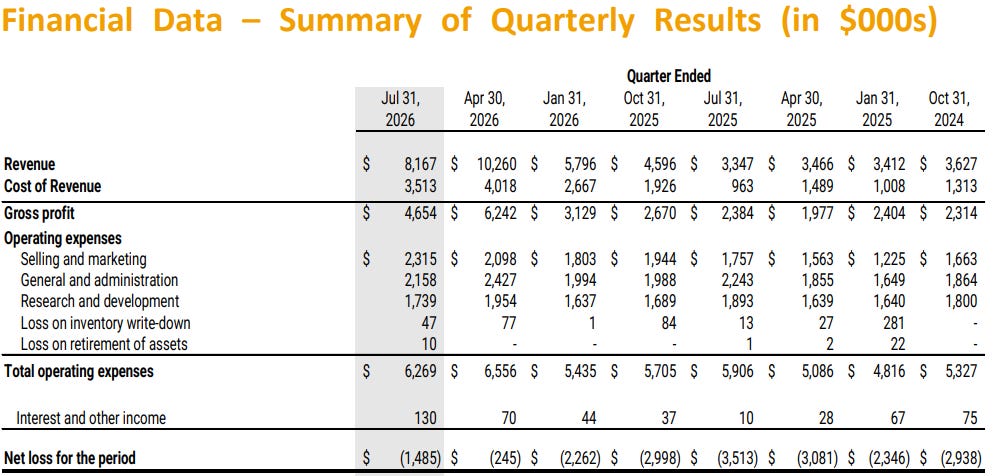
On the year, Xtract delivered $28.8M in revenue, a 108% increase over top of the $13.85M generated in 2025. Gross margin was off on the total year by nearly 800 basis points, ending the year at 57.9%. Despite that the company still put 84% more dollars on the gross profit line.
Total operating expenses rose by 13%, which is overall excellent conversion on their revenue and gross profit performances.
That resulted in a 40% annual improvement in operating losses. The problem here is if was still $7.3M, or about 25 cents for every revenue dollar generated.
The Q4 revenue results themselves are better than their overall annual results with revenue increasing by 144%. Gross margin was substantially down on a comparative basis (1430 basis points) from over 71% to 56.9%. That revenue increase of 144% shrinks to 95% more G.P. dollars as a results.
Expenses continue to be well controlled, only growing at 6%.
Net losses were slashed by 58% to a net loss of $1.5M vs $3.5M.
Summary:
Overall a pretty successful year, particularly in comparison to their 2025, but I’m closer to taking Xtract One off of my watchlist than thinking about taking a position here.
For the first time in 5 quarters, XTRA experienced a QoQ revenue decline, and we’re talking about 20% rather than a minor blip. That could also be a signal of things to come given new order bookings were down by 16% on the year and 64% over last years record Q4. Total backlog is up by 66% over last year but only $10.5 of it is anticipated to be recognized as revenue in fiscal 2027. That creates a $18.3M shortfall just to match off what they did this year in revenue.
I could be more forgiving at a cheaper valuation, or more encouraging fundamentals. As mentioned above, even with a 40% improvement in their loss from operations, they still lose over a quarter for each dollar in revenue they generate. Xtract isn’t even remotely close to being profitable on the EBITDA or even Adjusted EBITDA basis - and I’m someone who regularly calls AEBITDA bullshit. So why would I pay 5x revenue for this?
At current operational spending levels and margin achieved in 2026, their breakeven point is approximately $41.4M. They did $28.8M and their backlog and order book suggests growing on that could be a challenge.
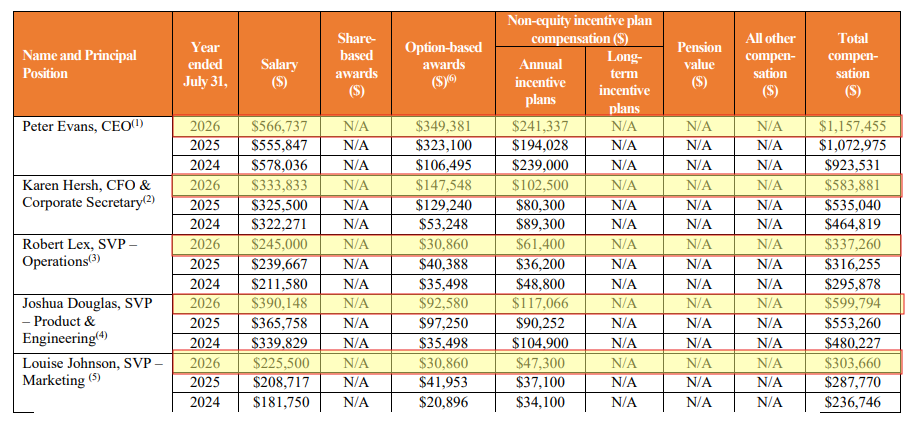
The C-suite raked in a total of $2.98M in total compensation for 2026, greater than 10% of revenues. $2.15M of it cash burning. That includes $570k in bonuses for a company losing 25% on the bottom line. At least the CEO made insider buys of $520k last month. Not exactly a compelling reason for me to get behind the stock.
Midway through the trading day and the stock is down 14% and by as much as 19% earlier in the session. It feels like the market is siding with my take so far. That is down over 50% from their early November high of $0.98.
The company was extremely lucky to be able to raise at $0.75 a year ago considering it only traded over that figure for a total of six days before the announcement. At least they have that balance sheet windfall to withstand what appears like a potentially tougher year.
Slim chance this stock sees $0.64 in the near future with 20M warrants expiring in April. Overhang much?
Downgrading to 2.5, even with the improved fundamentals and 14% cheaper price.
Disclaimer:
My intent is for my reviews to be a bolt on to due diligence that you have already completed. I receive dozens of review requests a week, therefore my own DD may be great or none whatsoever. Unless otherwise stated or implied, my opinions are on the financial performance of the company based on their most recent filings. I conduct these reviews to assist other retail investors whose research skills are limited when it comes to reviewing financial statements. I do not accept compensation of any kind from companies I review.
Wolf FINS Reviews are intended to be informational and are based on personal opinion. They are not intended to be financial advice, and all readers are encouraged to perform their own due diligence prior to their investment decisions, including discussions with their investment advisor.