


This review is the result of another poll from the Wolf Den discord. Users had a choice between MYID, SPN and CHER. With 45% of the vote, we will be reviewing Reklaim Ltd.
I initially thought that this would be my first coverage of the company. It turns out that isn’t true. I rewarded them with a mediocre 2.75 star review two and a half years ago. Sometimes when you review so many stocks, you’ll forget some and to be honest, back then they weren’t exactly memorable.
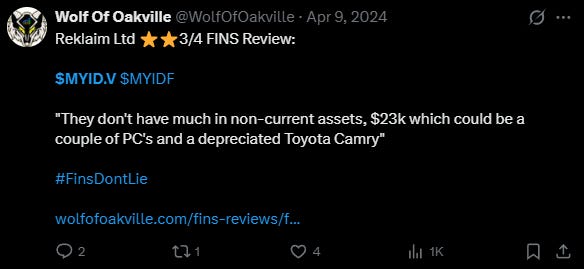
The review was completed prior to moving to Substack, but I moved it over from the archive and can be viewed below for comparison purposes.
Reklaim ($MYID.V) FINS Review
Fins just dropped and at a first glance there looked like there could be something here. Market approves, up 11.1% so far this morning, but let’s see if this gets my approval as well.
Investors appear to have liked these financials very much, sending the stock up by 64% since their release to 19 cents to a $24M market cap valuation. That is a 89% gain over the past year but 500% from their lowly lows of just 3 cents back in March.
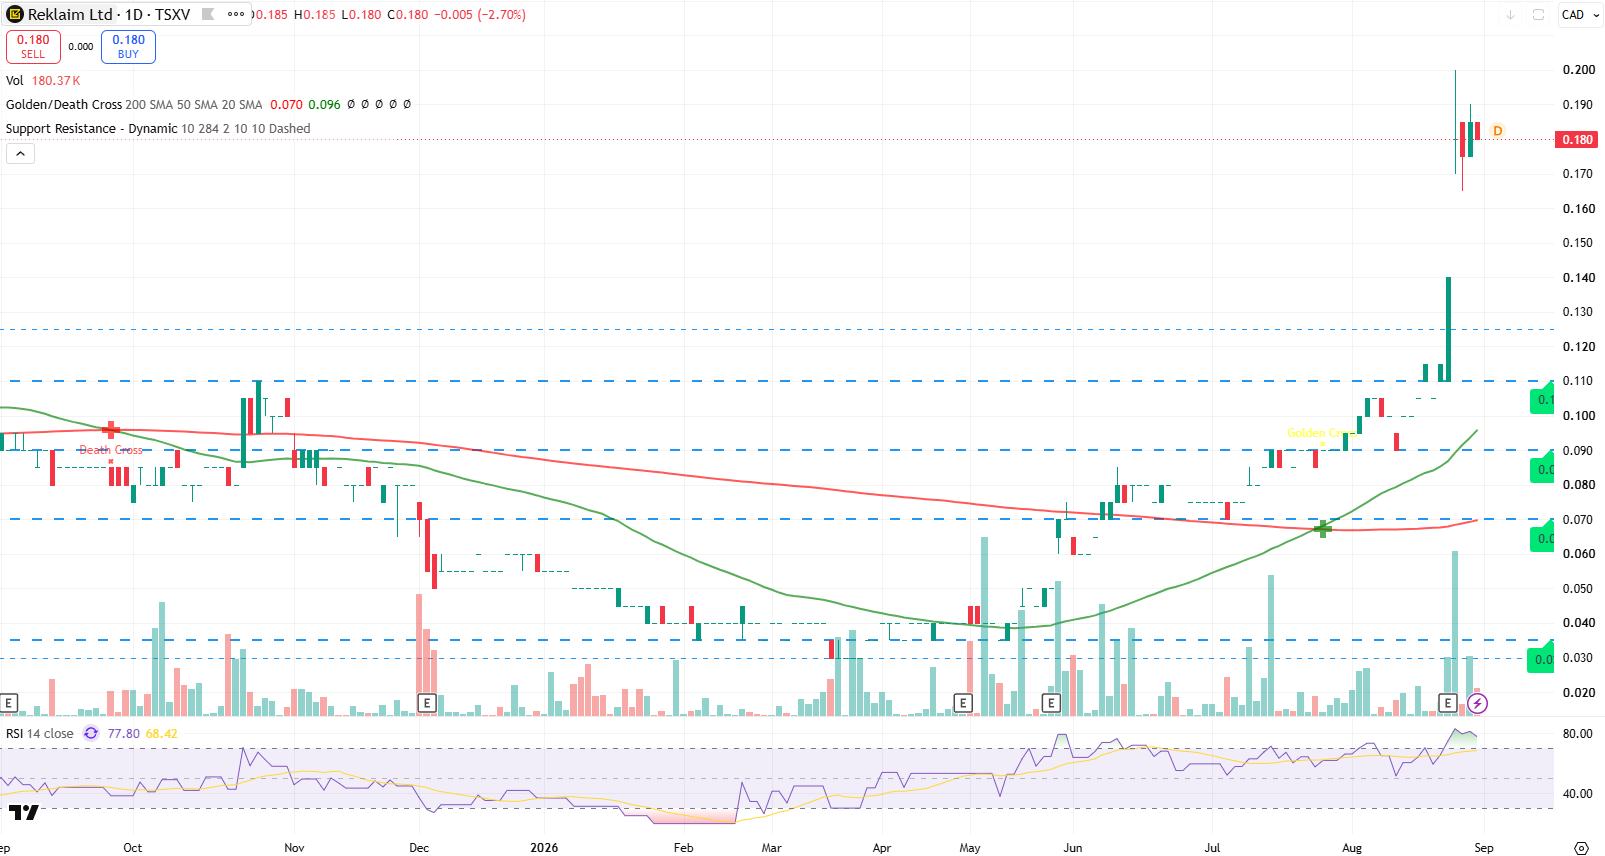
When I reviewed the stock nearly thirty months ago, it was in the 14 cent range at a $16M market cap, so if you were a MYID shareholder for all of that time, you were likely in the red until last week.
Reklaim has an interesting and unique business model - they allow consumers to opt-in to share specific pieces of data with brands, agencies, and companies in exchange for compensation from the use of their personal data.

For a quick way to best understand what Reklaim does, I’ve attached a 7 minute YouTube video below that may explain it the best.
Keir from TokStocks has also covered the company, and you can find CEO interviews from his Substack.
Let’s get into it and see if MYID is worthy of this recent bounce, and how that old Toyota Camry is holding up.
(Free release on Wednesday Sept 9th)
Balance Sheet:
Reklaim has a pretty solid looking current ratio of 2.6 that consists of $1M in cash, $1.5M in receivables and $120k in other short term assets against just $1M of liabilities due over the next twelve months.
The good news is their cash position offsets all of their one year financial commitments which include a small $65k loan at 5.3% which matures at the end of this year.
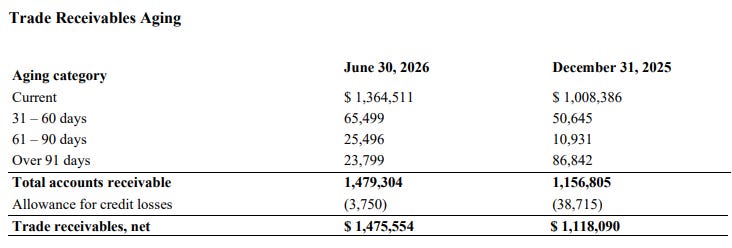
When a company’s A/R makes up more than half of the company’s total assets, never mind just current, it’s worth checking the aging report. I’m happy to report that they look excellent. While their 60-90 typical terms aren’t the best for a small organizations cash flow, the A/R and history of write offs look quite good.
In terms of other debt, they have $455k in debentures as 12 points converting at 10.5 cents with an expiry of Oct 2028.
Pretty clean and no issues here. Those couple of PC’s and that aging Toyota Camry must have a lot of clicks on it now as they only have $15k in long term assets ($23k when I last looked at them in the Spring of 2024).
Cash Flow:
Pretty solid six month cash flow numbers for a company with just $2.6M in total assets. Through the first half of their fiscal year they generated $850k of operational cash flow. That number includes burning $220k in Q1 meaning they generated nearly $1.1M in this recent quarter.
The $850k of OCF thus far compares to burning $43k at this stage last year, so the last couple of quarters have been quite a turnaround for the business.
Reklaim is also buying back stock, $321k worth so far this year.
No investing activities in the past couple of years. That Camry is still running strong.
Share Capital:
124.4M shares outstanding, 6.1M shares less than the beginning of the year through their aggressive buy back strategy
2.4M warrants all related to their debentures, all ITM at 14 cents. 3.2M also expired at that price earlier this year
8.3M options outstanding, all but 125k are currently ITM. 3.6M granted YTD
1.75M RSU’s outstanding, with 1.1M granted YTD
4.3M in shares scheduled to convert in Oct 2028 or earlier (not including interest)
30% insider ownership (per Yahoo Finance), the majority of which held by the CEO
No insider activity in the last twelve months
After ripping on them pretty good a couple of years ago for their bloating float (it had diluted by 83% over the past two years back then), they have done a better job of it since. The aggressive buybacks are notable at 6.1M shares just through their first six months. What is also worth pointing out is they have awarded 4.7M in stock options and RSU’s in that same time frame under their 10% rolling plan. In fairness, much of their previous year awards have expired worthless in terms of stock options. It appears they are giving themselves back a little something here, and perhaps that is deserved given their improved performance.
Their fully diluted float including ITM securities is around 141M giving them an implied market cap of about $25.4M
Income Statement:
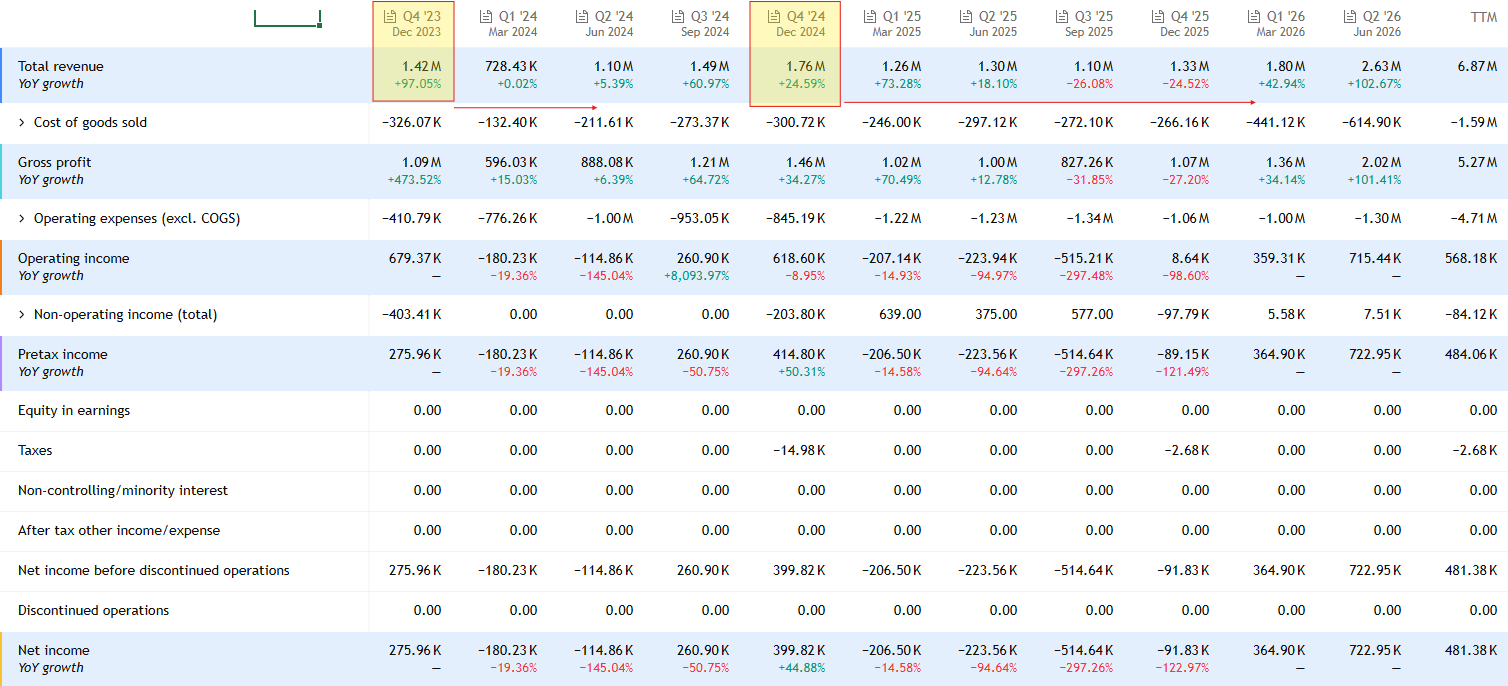
A heck of a start when you can throw down a triple digit increase over last year. Revenue in the quarter of $2.63M, a 103% increase over the $1.3M achieved in the comparable quarter. A slight 50 basis point hit in their margin rate, but who is going to complain at 76.6%? Gross profit dollars increased 102%.
Maybe most impressive is this was done with only 6.2% increased operational spending. Given there is little depreciation or amortization involved with their two Commodore 64’s and 1994 Toyota Camry on the balance sheet, we can safely assume these are all cash burning aside from their SBC costs.
Jokes aside, and even given the minor decrease in margin rate, this is worthy of a Wolf Trifecta quarter.
That small 6.2% increase in expenses amount to $77k. Therefore the difference of their $1.02M in GP dollars less that equals a $960k turnaround in profitability. $723k vs a $223k net loss last year. Their revenue was also up 46% sequentially and net income by 98%.
Summary:
In short, this is a hell of a much better company fundamentally than I looked at back in April of 2024. It also very much appears they are deserving of their recent large bounce since earnings. I don’t say that often and quite frankly I wasn’t expecting to say that about Reklaim.
Where they go from here and how to properly value them presents some different challenges however.
On a TTM basis, they look very expensive, a 49 P/E, a 39 EV/EBITDA ration and at 108x cash flows.
Extrapolating their current YTD performance paints a different picture. That potentially looks on the cheaper side at a 10.7 P/E, a similar EV/EBITDA and 14x cash flow. If you wanted to extrapolate the quarter (I won’t because that’s silly) it gets cheaper still.
The question is where do they go from here? I wish I had a better feel as to how lumpy their revenue might be. In Q4 of 2023 they achieved $1.42M and it took them three quarters to best that. In Q4 of 2024 they achieved $1.76M and then took them FIVE quarters to surpass that.
They launched a consumer facing subscription service last year which drives some recurring revenue, but I can’t find any data on how big a portion of that makes up their total revenue. My guess is if it was fairly significant, they would be shouting it at us.
That certainly seems to be Reklaim’s style though. Not much in terms of news releases or keeping retail investors apprised on a regular basis. For longs that can be a frustrating experience, so if you’re thinking about taking a swing here, keep that in mind.
But despite some of the lumpiness, the business is growing fairly consistently overall. It’s hard to envision a scenario where consumer will want less control of the data so I think their product will only continue to attract new people. The next two upcoming quarters present another opportunity as well. Q3 is the softest revenue performance of their last nine quarters AND their worst on the profitability line almost as far back as you can look. Q4 isn’t much stronger comp wise so there is a huge opportunity for them to finish out the year strong.
Buying at 52 week highs can be an uncomfortable experience in the microcap world. But I did just that today with a starter position. Maybe it’s a long swing into their annual financials next year, maybe a longer term hold. We’ll see.
Big upgrade to four stars. I just love myself a comfortable old Camry.
Disclaimer:
My intent is for my reviews to be a bolt on to due diligence that you have already completed. I receive dozens of review requests a week, therefore my own DD may be great or none whatsoever. Unless otherwise stated or implied, my opinions are on the financial performance of the company based on their most recent filings. I conduct these reviews to assist other retail investors whose research skills are limited when it comes to reviewing financial statements. I do not accept compensation of any kind from company’s I review.
Wolf FINS Reviews are intended to be informational and are based on personal opinion. They are not intended to be financial advice, and all readers are encouraged to perform their own due diligence prior to their investment decisions, including discussions with their investment advisor.