


I’ve returned from back to back vacations and while I would love to tell you I’m full of piss and vinegar, I’m still very much still adjusting from being on European time for the past couple of weeks.
In spite of the jetlag, I have been eager to hit the keyboard, and I will get back in the saddle with this 2026 Wolf Pick who released their Q1 numbers nearly two weeks ago. The stock has performed decently since the pick, up 21.5% and up as high as 50%. It is safe to say that the performance since these numbers were released to the market has been rather muted.
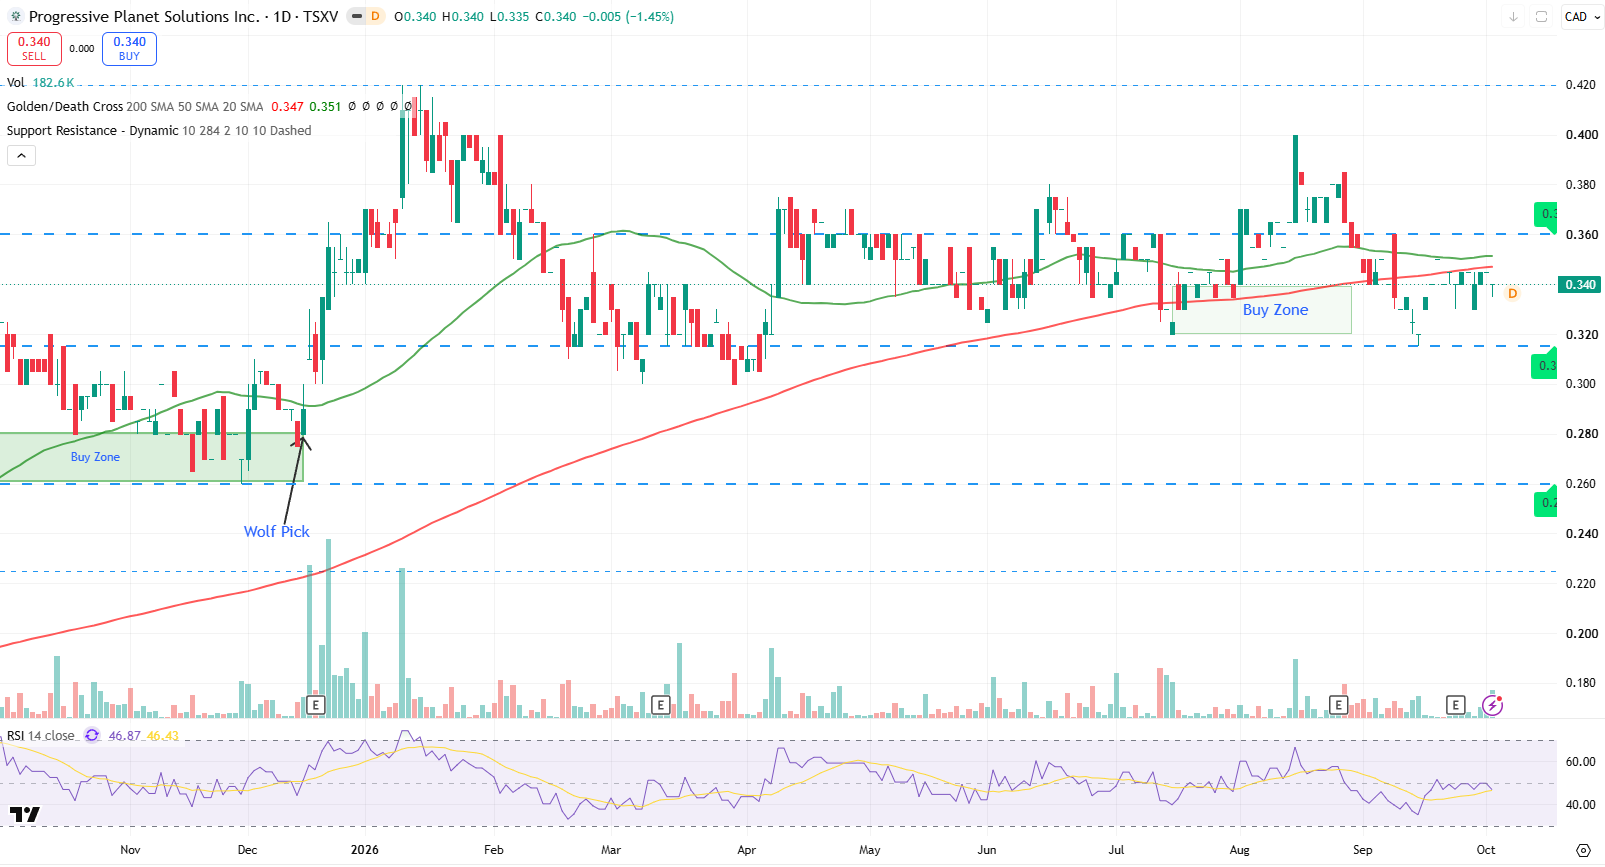
The muted market response comes at a time when the company achieved their highest quarterly revenue number ever. One would then assume there are other issues within these numbers. Let’s dig in to find out what those might be.
The Company:
If you are new to the Progressive Planet story, they are a CleanTech and manufacturing company with products in over 10,000 retail stores across North America. They focus on the cement, agricultural and animal care sectors. In addition to their established, profitable product lines, they have a number of capital projects underway including PozGlass, meant to disrupt the cement production industry. Attached below is their most recent investor deck.

You can also read why I selected them as a 2026 Wolf Pick here.
Balance Sheet:
PLAN’s current ratio improved in the quarter from 2.0 to 2.4. That consists of $2.5M in cash, $1.8M in A/R, $3.1M worth of inventory and $400k in prepaids overtop of $3.3M in liabilities due over the next twelve months. $400k of those current liabilities are in the form of deferred grant income.
Inventory figures are notably larger, up by 27%. The company’s rationale is to support higher sales levels and stockpiling raw materials ahead of the winter months.
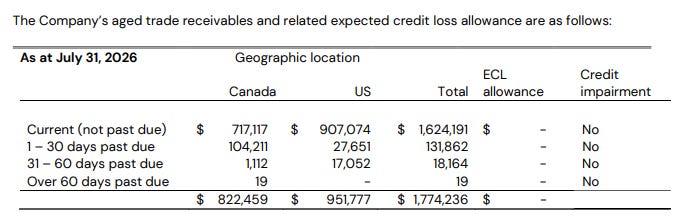
Their A/R aging report continues to look solid with 92% of receivables listed as current with little to no concentration risk.
Progressive Planet has $5.3M of debt, the vast majority under a 23 year mortgage with BDC at 5.05% interest.
Cash Flow:
Operational cash flow came in soft in Q1 compared to last year, burning $128k vs generating a half million dollars in the comparable quarter last year. You would have to go back sixteen quarters to find the last time the company burned cash in a quarter.
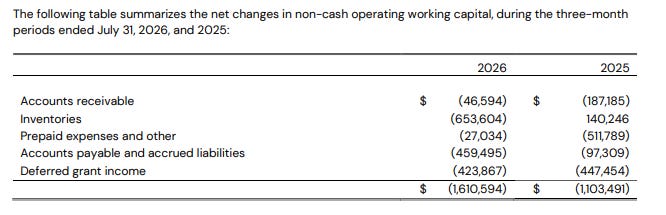
The causes are two fold. Firstly, net income was down by 31% from $1.6M to $1.1M, and we’ll get to those reasons when I cover the income statement. Secondly was working capital adjustments which all went the wrong way for OCF purposes. The notable lines were from inventory purchases in Q1, and a significant reduction in their accounts payable.
On the investing side, Progressive Planet invested $436k in PPE in the quarter along with $137k in mineral property additions across all three of their sites in B.C. Most interesting was their disposal of shares from two public companies for proceeds of nearly $1M. I’m very happy to see this personally- let me make the stock trades while the company works on the business.
PLAN also made $140k of debt payments and received $165k from stock options.
Overall the company improved their cash position by 13% from the start of their fiscal year a quarter ago. This would have looked significantly worse if not for the sale of their investments. Due to the working capital adjustments in Q1 I’m not overly concerned and feel this quarter is just a one off, but watch this space when they report Q2 sometime in late December.
Share Capital:
110.9M shares outstanding, 1.0% dilution over the past year through exercised options
6M options outstanding - all ITM.
31% insider ownership with a minor stake from one institution. (per SimplyWallSt)
$52k worth of stock sold by one insider in the quarter - interestingly the same individual who let ITM options expire a month earlier
Overall the company has a history of maintaining a well managed float
Income Statement:
As mentioned in the opening, a record revenue quarter of $7.3M, 23.3% up from the comparable quarter’s $5.9M last year. Gross margin declined by over 400 basis points from 38.5% to 34.4%, therefore gross profit dollars only improved by 10% on 23% more revenue.
Total operating expenses were relatively flat but share based compensation was $225k less than last year. Excluding SBC, operating costs rose by 18% mainly caused by much higher R&D spending ($473k vs $138k).
With almost no SBC costs in Q1, operating income grew more than revenues at 29%. However due to less grant income ($213k), loss on investments ($117k) and less deferred tax recovery’s ($367k), net income of $1.11M came in $488k less or 31% than last year.
Summary:
Outside of their record revenue numbers, there are few other headlines worthy of celebration. By the same token, other than the loss on investments from their two previous public holdings, it’s difficult to place the blame for the lower profitability on poor managerial decisions.
The gross margin decline was fairly significant. 410 basis points on their record revenue numbers equates to $300k. While their decline in margin was partially due to product mix, the most significant hit to their costs of sales were freight costs which increased by 50%, or $413k to last year. That was driven by the price of diesel and if that caused issues in their first quarter, it is surely going to extend at least into Q2 and perhaps beyond.
The rest of the variances from deferred taxation and grant income are profitability lumpiness that I believe we will continue to see throughout their fiscal 2027. The $840k of TTM net income isn’t a head turner for this $38M market cap, but when you factor in the half million slotting fee which is now paying dividends with Tractor Supply and the $1.2M one time write down of their old mining asset, it gets much more attractive given their growth and long term potential of their PozGlass initiatives.
Even though it has nearly been a couple of weeks since these results were published, outside of the press release, investors have yet to hear from leadership on these results. That changes tomorrow as their CEO will be sitting down for an interview with Radius Research. You can register for that webinar here.
I will be tuning in for PozGlass pilot plant updates, more detail on future R&D and capex spending along with other initiatives.
For now, I think the company did more than enough to maintain the 3.5 star rating from last quarter. Holding and looking for reasons to add to my position.
Disclaimer:
My intent is for my reviews to be a bolt on to due diligence that you have already completed. I receive dozens of review requests a week, therefore my own DD may be great or none whatsoever. Unless otherwise stated or implied, my opinions are on the financial performance of the company based on their most recent filings. I conduct these reviews to assist other retail investors whose research skills are limited when it comes to reviewing financial statements. I do not accept compensation of any kind from company’s I review.
Wolf FINS Reviews are intended to be informational and are based on personal opinion. They are not intended to be financial advice, and all readers are encouraged to perform their own due diligence prior to their investment decisions, including discussions with their investment advisor.