


I began yesterday’s WWW “What’s Wolf Watching” article discussing how bad things have been for microcaps of late. The markets told me to hold my beer with the major indexes losing between 1 - 2.5% and the TSXV losing 2.7% on Monday.
An inopportune time to be releasing financials, perhaps even pretty good ones for iFabric.
Even with stock giving up 3.6% on their earnings released yesterday morning, they are still up 168% from the Wolf Pick last December, but the $4.02 close is nearly 30% off their 52 week high experienced in July.
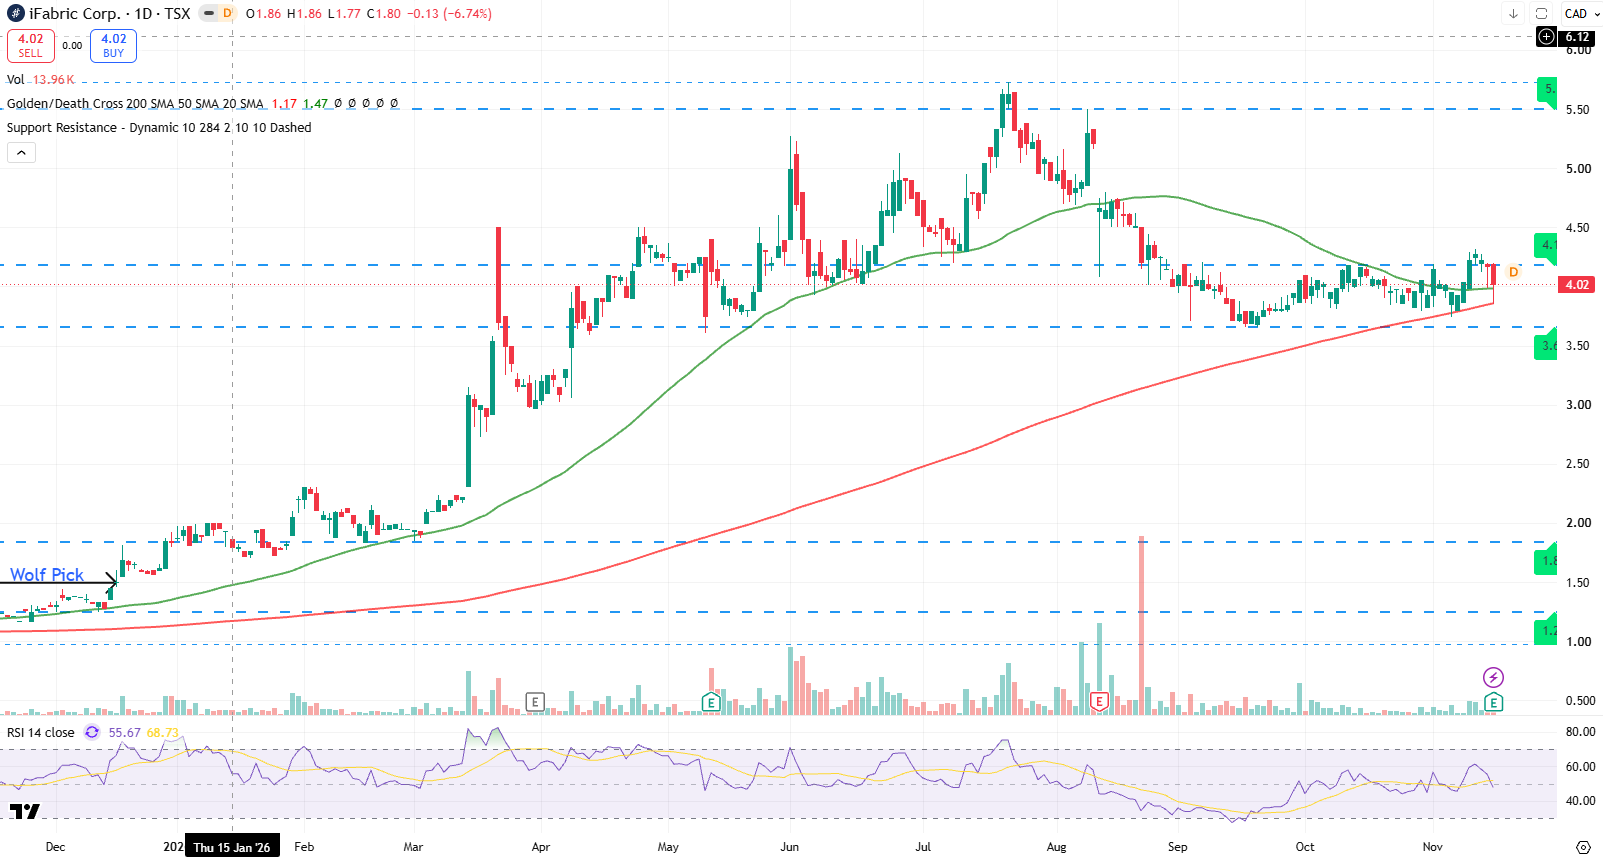
The headlines were once again solid, a record Q3 with revenue 26% better than the comparable period, with improved margins that helped drive a doubling of their net earnings.

That certainly sounds worthy of a better fortune than what the market rewarded them with. Let’s dive into it to ensure there were no fly’s in the ointment, and if there will be any change to my previous back to back 3.5 star ratings.
The Company:
iFabric is an apparel manufacturer that operates in two main segments - intelligent fabrics and intimate apparel. Historically, the core of their business has been in the high margin intimate apparel business line, with their recent growth and most of their future opportunities within intelligent fabrics and textile technology. Recent success has been within their medical scrubs launches into new retailers, including Walmart, Costco and Target. iFabric is on pace to double revenues in 2026.

Balance Sheet:
The balance sheet and liquidity are extremely strong with a current ratio of 5.3 (up from 4.3 last quarter) that is made up of $20.7M in cash, $11M in receivables, $16.8M worth of inventory, $5.2M in deposits and prepaid expenses overtop of just $10.1M in current liabilities. Their cash position alone covers their twelve months commitments by a factor greater than two.
Technically their current ratio and liquidity situation are better than it appears as their $3.6M in bank debt is listed as current due to IFRS rules. It is amortized over a 25 year period ending in 2055 and the company only expects to pay $22k in monthly installments over the next twelve months. The company also has an unutilized $12M line of credit and $2.5M trade facility.
iFabric does not disclose an A/R aging report quarterly, but the $11M is consistent with last quarter on a 26% revenue increase with minor expected credit losses so no yellow flags are apparent. Inventory levels are down 20% from the start of their fiscal year.
Cash Flow:
Operational cash flow is a little messy with $1.5M generated through their first nine months compared to a cash burn of $2.7M a year ago.
Prior to working capital adjustments, their OCF is $5.9M vs $750k last year, nearly 8x better. Reducing their accounts payables by 54% from the beginning of the year and prepaid expenses and deposits makes their total OCF understated, and I would expect a much improved fourth quarter, more in line with their profitability.
The biggest reason their balance sheet is in such great shape is the $21M the company raised earlier this year. iFabric also received $1M into the treasury from exercised options and they utilized that Q2 private placement to eliminate the $6.6M on their line of credit.
Overall, IFA’s cash position sits at $20.7M, 450% better than where they started the year at $3.8M
Share Capital:
37M shares outstanding, with 22% dilution over the past year, mainly due to their capital raise
1.3M options outstanding, all ITM. 500k exercised in Q3
Zero warrants with all 2.9M outstanding last year expiring unexercised.
Insider ownership now sits at 50%, down considerably with the private sale at the time of their raise
Income Statement:
Revenues increased in the quarter by 26% to $11.4M, up from $9.0M. Gross margin was up by a very impressive 880 basis points from 30.2% to 39% which drove gross profit dollars 62% higher on only 26% more business. The margin improvement is largely due to the product mix with significant growth in their intimates business which grew by 218% in the quarter.
Operational leverage wasn’t great in the quarter with operating expenses 33% higher on those 26% improved revenues with G&A costs up by 31% and selling costs up by 30%. After recognizing $925k in tariff refunds in Q2, it appears U.S. Customs stiffed them for $106k, which the company recognized as an expense in Q3.
Earnings from operations were nearly 3x better than last year at $1.48M and after interest income of $120k due to their beneficial cash position, net earnings came in at $1.08M, double the $543k they achieved last year. It’s also notable that iFabric achieved that despite a 6x in increased tax burden ($600k vs $100k).
YTD Performance:
Revenue up 121% from $21.9M to $48.4M
Margins declined 130 basis points from 33.4% to 31.7%. Gross profit dollars increased by 113%
Operational leverage looks better YTD with operating expenses increasing by 29%
Operating income 18x better than last year. $6.9M vs $377k
Net income of $5.03M, 11x better than last year
Income tax burden $2M higher
Summary:
Just another solid quarter out of iFabric.
If there is a surprise or some perceived weakness it’s in their intelligent fabric line which decreased by 32% to the comparable quarter. Even with a one time $2.5M order from last year, that feels light. Of course this decrease comes after Q2 where that segment was up by 94% and their incredible Q1 which was up 305%, so take that slight disappointment with a grain of salt.
The lumpy and somewhat messy OCF this year is explainable and should balance out in Q4 which should show more net income to cash flow conversion.
News flow has been on the slow side as the market hasn’t had any updates regarding recent retail store expansion. Walmart which was allegedly clearing out competitor products to make room for expanded lines has yet to come to fruition. The market also has several other initiatives to potentially look forward to. EPA approval for their kill claim, news on Target, performance bedding, Roots programs in Costco and European swimwear.
Adelaide Capital will be hosting a call to discuss these earnings today at 11 am. You can register for that here.
On the unexpected, pleasant surprise front, the Nudish rebrand, targeting a younger demographic appears to be going extremely well with great numbers over the past two quarters, including tripling the revenue segment here in Q3. That really helped the quarter on the margin line which travelled all the way to the bottom line.
If the forecast of doubling revenues in 2026 is still accurate, that would imply a $15M Q4 when the company reports next in the new year, and that would be 43% increase to close out the year,
In terms of current valuations, iFabric’s market cap currently sits at $149M. That puts them at about a 33 P/E on a TTM basis with EV/EBITDA at around 18. That’s on a TTM basis with a negative profitability quarter last year. With a $15M revenue and $1M net income quarter that puts their P/E around 24 with an EV/EBITDA of around 15. That feels relatively reasonable right here with many initiatives and potential catalysts to come.
Almost upgrade worthy, but keeping 3.5 stars and saving that upgrade potentially for early 2027.
Disclaimer:
My intent is for my reviews to be a bolt on to due diligence that you have already completed. I receive dozens of review requests a week, therefore my own DD may be great or none whatsoever. Unless otherwise stated or implied, my opinions are on the financial performance of the company based on their most recent filings. I conduct these reviews to assist other retail investors whose research skills are limited when it comes to reviewing financial statements. I do not accept compensation of any kind from companies I review.
Wolf FINS Reviews are intended to be informational and are based on personal opinion. They are not intended to be financial advice, and all readers are encouraged to perform their own due diligence prior to their investment decisions, including discussions with their investment advisor.