


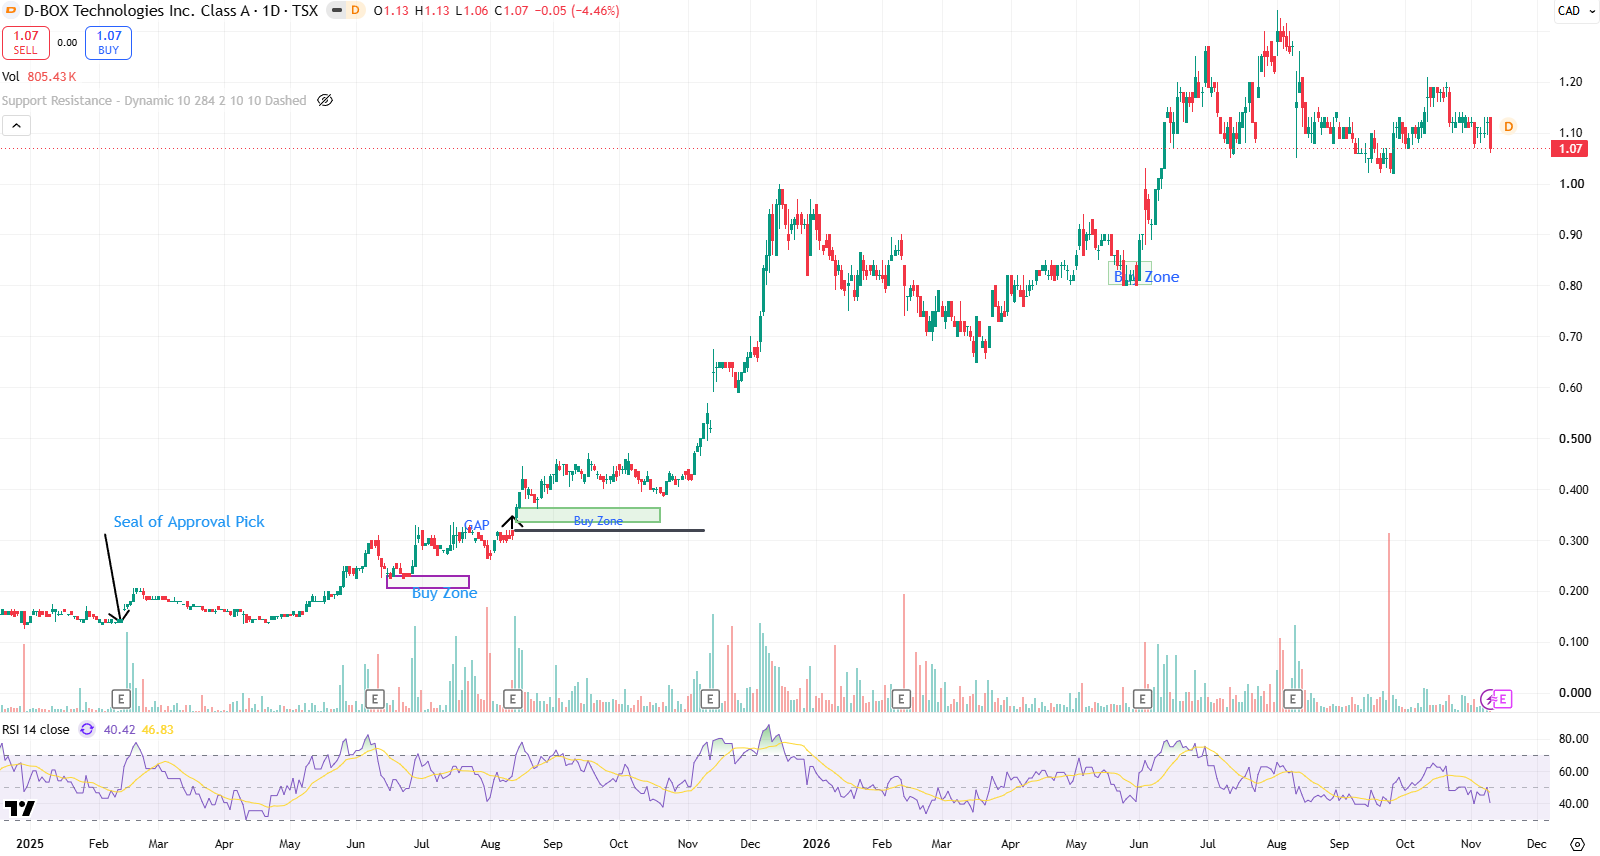
It’s been quite the ride for anyone on the D-Box train over the last seven quarters when it was selected at $0.145 with three buy zones along the way and coming 11 cents shy as a nine bagger when it peaked at $1.34 back in July.
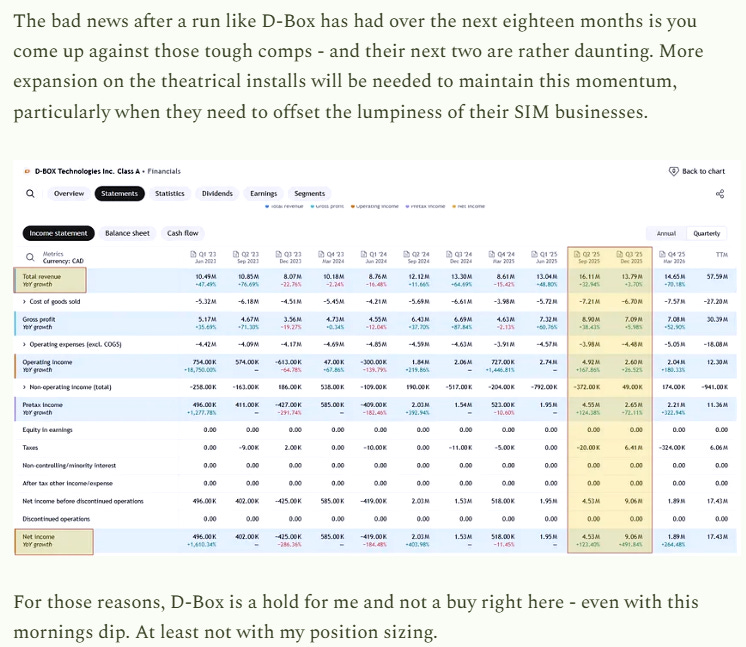
If you read my highly rated 4.5 star review last quarter, I discussed what I referred to as the Achilles Heel in the business (lumpy SIM revenue), the need for new installations to continue the momentum, and the very tough Q3 and Q4 comps they would be up against.
Most D-Box investors and followers felt quite good about the royalty revenue coming into this quarter based on Cineplex numbers, particularly around premium and their new “motion” seating metric, along with numbers out of IMAX and others. The problem is royalty revenue makes up between 25-30% of total revenues and there isn’t much of a weather vane from quarter to quarter on their other two main segments.
I had peeled off some profits earlier in June. Now that their Q3 results are out, do I wish I had taken more off the table? Spoiler alert - the lede of the news release was on gross margin, so that’s not a good sign.
The Company:
D-Box Technologies, Inc. engages in the design, manufacture, and sale of haptic motion systems. Its products include movie theater, sim racing, and simulation and training. For my purposes, I like to consider the company having three revenue streams. The first is Theatrical installs - more simply, adding their D-Box seating into new theatres. Secondly is royalty revenue derived from those DBox seats in theatres. If you have paid to sit in one, a portion of that ticket price goes to the company. Lastly is their Simulation business from SIM racing products and arcades to client system training.
Balance Sheet:
As I stated last quarter their balance sheet is and remains cleaner than a nun’s conscience. Their current ratio stands at 4.5 and consists of $19.9M in cash, $10.2M of A/R, $6.9M worth of inventory and $1.5M of other short term assets over top of $8.5M in liabilities due over their next twelve months. Their cash position alone covers those liabilities by a factor of 2.3 so the remain very liquid.
They are virtually debt free with just a small Canada Economic Development loan at 4% with $278k remaining and will be extinguished by December of 2027.
No issues here.
Cash Flow:
After a very soft operational cash flow number in Q1, D-Box delivered $4.05M of OCF in Q2 vs $1.34M last year for a 202% improvement over last year. That brings them to $5.08M generated YTD vs $4.17M through six months, 21% better.
D-Box utilized $555k on assets YTD, paid down $100k of debt and bought back $1.9M worth of stock.
Overall their cash position has improved by 13% since the start of their fiscal year.
Once again, no issues here.
Share Capital:
221M shares outstanding, down 1.7M shares from the start of the year via use of their NCIB
15.6M options outstanding, all ITM with 2.8M awarded YTD and 150k exercised so far this year.
410k SAR’s
1.9M RSU’s, 450k granted YTD
600k DSU’s all granted in 2026
16% institutional and 3% insider ownership
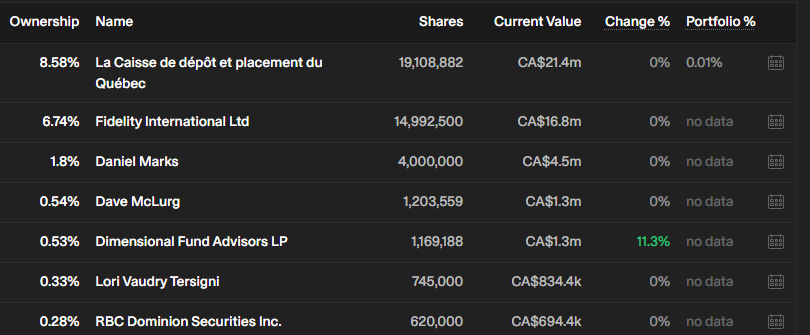
Mixture of insider buying and selling with the audit chair and largest insider, reducing his holdings by 38% over the past year
Income Statement:
Here’s where DBO investors collective asses begin to pucker up.
Total revenues came in at $12.1M, 25% lower than the $16.1M achieved in the same quarter last year. Gross margin was strong at 63.3%, a full 800 basis points better than the comparable quarter. That helped to lessen the revenue decrease blow of 25% with gross profit dollars narrowing by 13%.
Operating expenses were up by 18% on less sales and gross profit dollars. Selling and Marketing rose by 54% and Admin costs rose by 27%. R&D costs were down 28%.
At the bottom, net income came in at $2.6M, 42% lower than the $4.5M achieved last year.
On a YTD basis through six months:
$25.5M of total revenue, down 12.5%
Gross margin up 570 basis points to 61.3%
Gross profit dollars decreased by 3.6%
Total operating expenses increased by 4.9% led by Sales and Marketing expense by 25%
Net income of $5.56M, a decrease of 14%
Summary:
If you just looked at the quarter and YTD numbers without the comparison to last year, $25.5M of revenue and putting 22% of that figure on the bottom line looks pretty good in microcap circles.
Unfortunately, that isn’t how the world works.
The cash flow improvements are legitimate though and it does support some of the company’s rationale on the call.
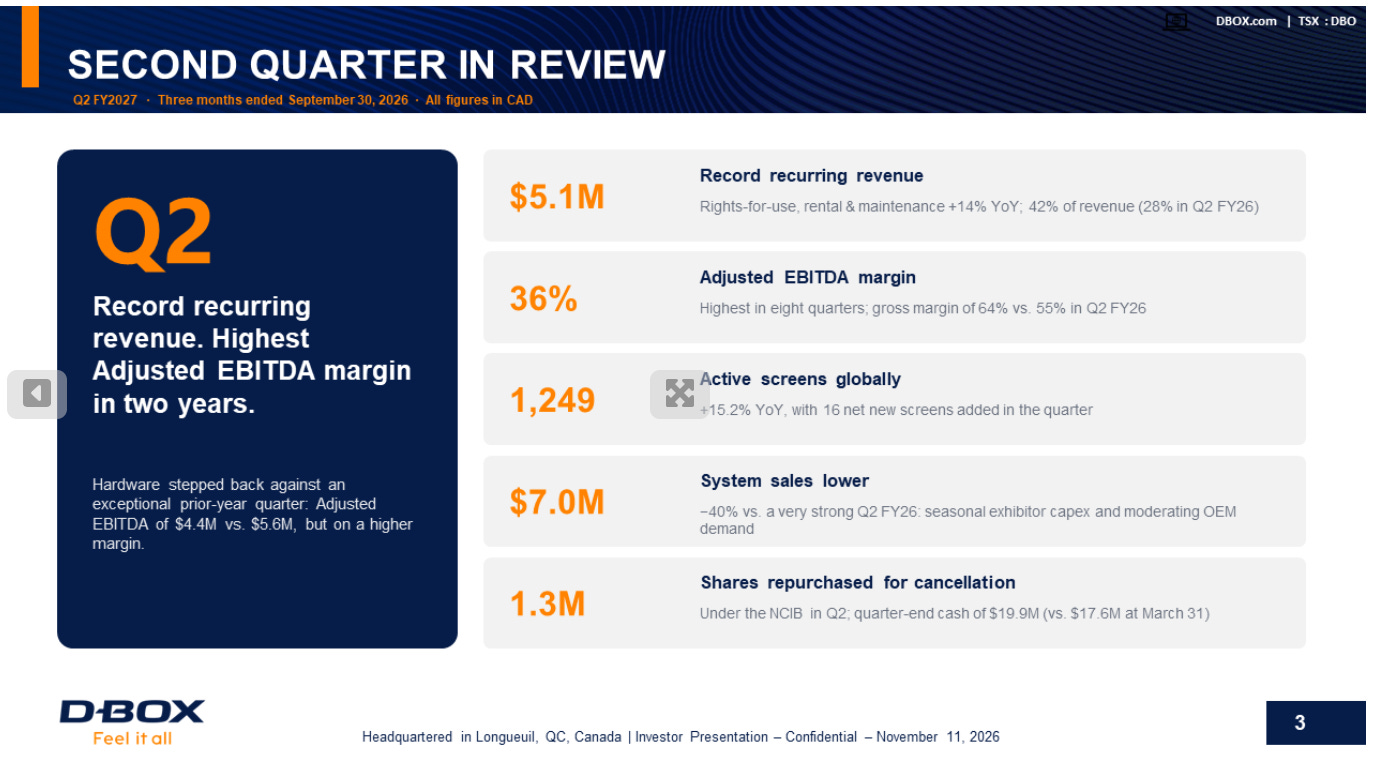
I don’t like using AEBITDA figures, but company's who shit the bed on net income love to use this figure, and that rationale is used in a stronger fashion when share based compensation costs are higher. That is the case here with $1.3M in SBC costs vs just $187k a year ago.
Ultimately I don’t have a problem with this based on the turnaround of the business in the last eighteen months. What I do take issue with is the company touting the 1.7M of shares repurchased through their NCIB and saying they are “returning value to their shareholders”. I say this because at the same time they bought back those 1.7M shares, they issued 2.8M options, and another 1.5M via SAR’s, RSU and DSU’s.
Shareholders are very likely about to take an ass whooping in early trading this morning - some of it deserving but it will likely be over done, so if you’re looking for a dip, this could be an opportunity.
While I put some warning signs out there regarding the lumpiness of two streams of their revenue, these results are probably worse than one could have expected.
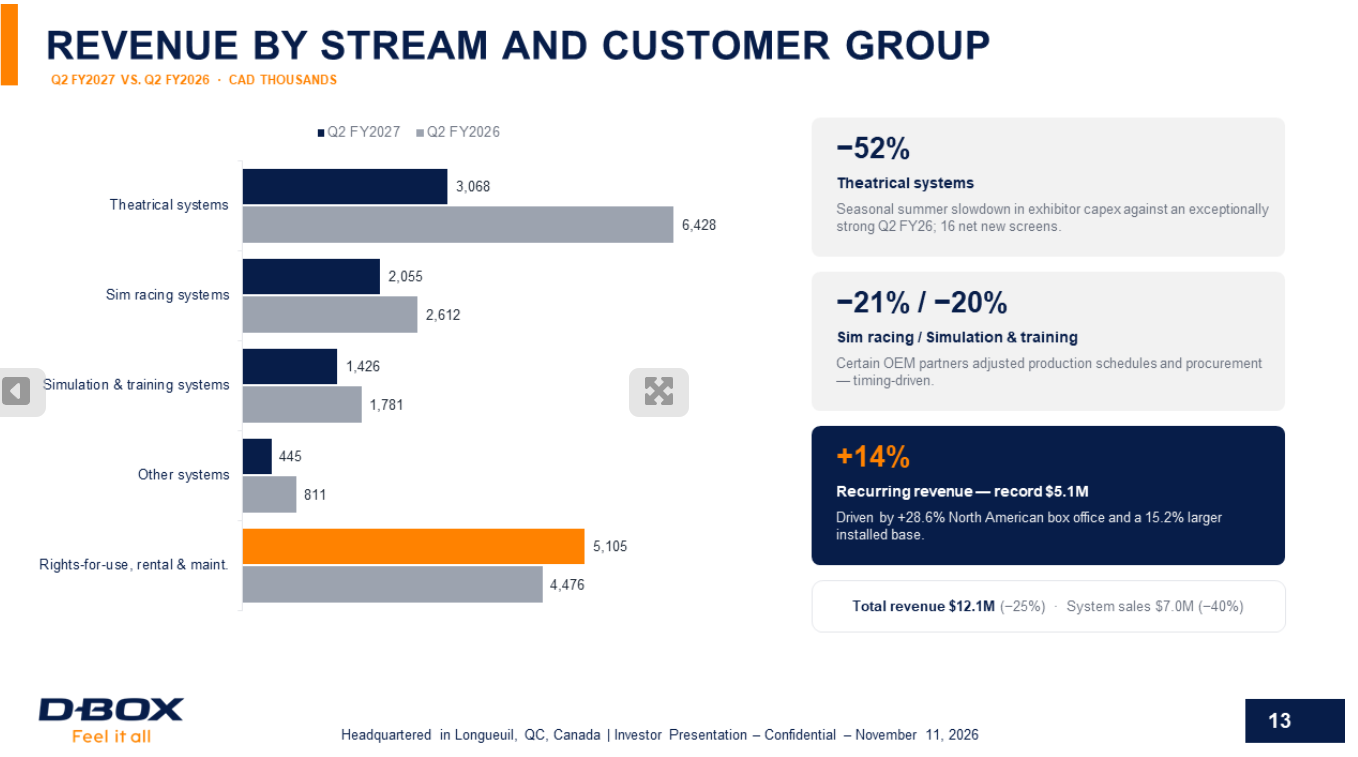
Theatrical sales were down 52% with only 16 new screens in the quarter and their SIM business were down by 20%. Even their royalty business of 14% were softer than expectations based on the box office hype over the past couple of weeks.
So how should a “worse than one could have expected” quarter now be viewed in the larger macro picture?
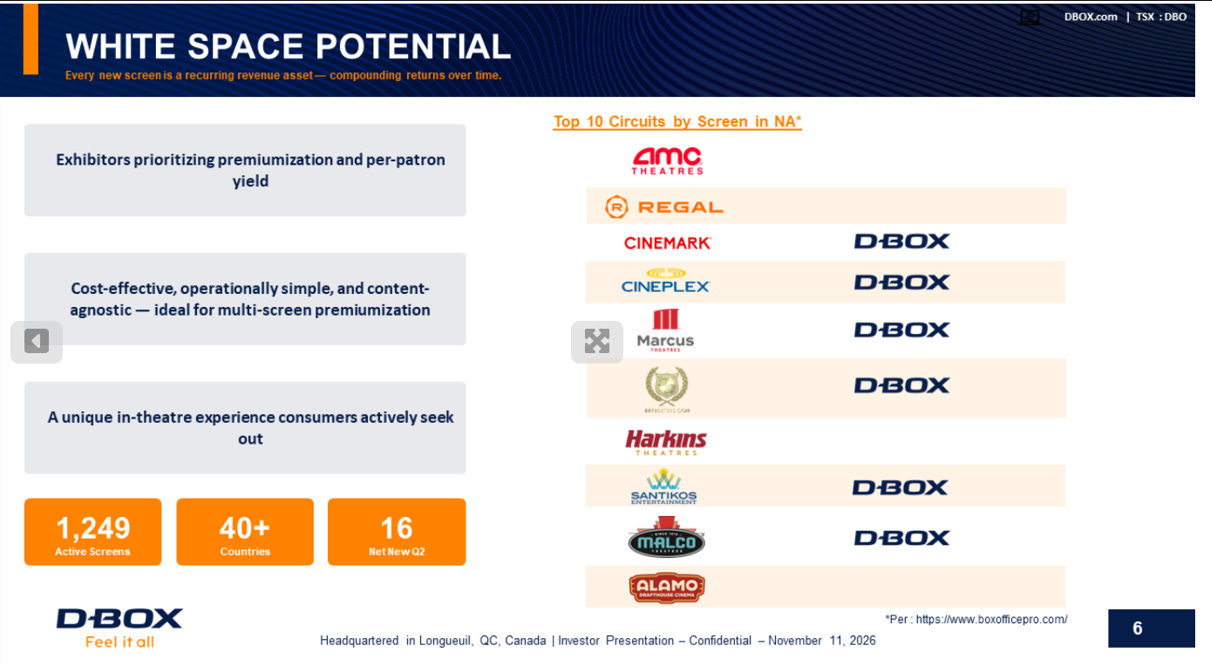
The TAM or opportunity is still massive considering they do not have a DBOX screen in the two largest theatre chains in North America. A foot in the door here would be a game changer and the CEO was bullish on those prospects during the conference call.
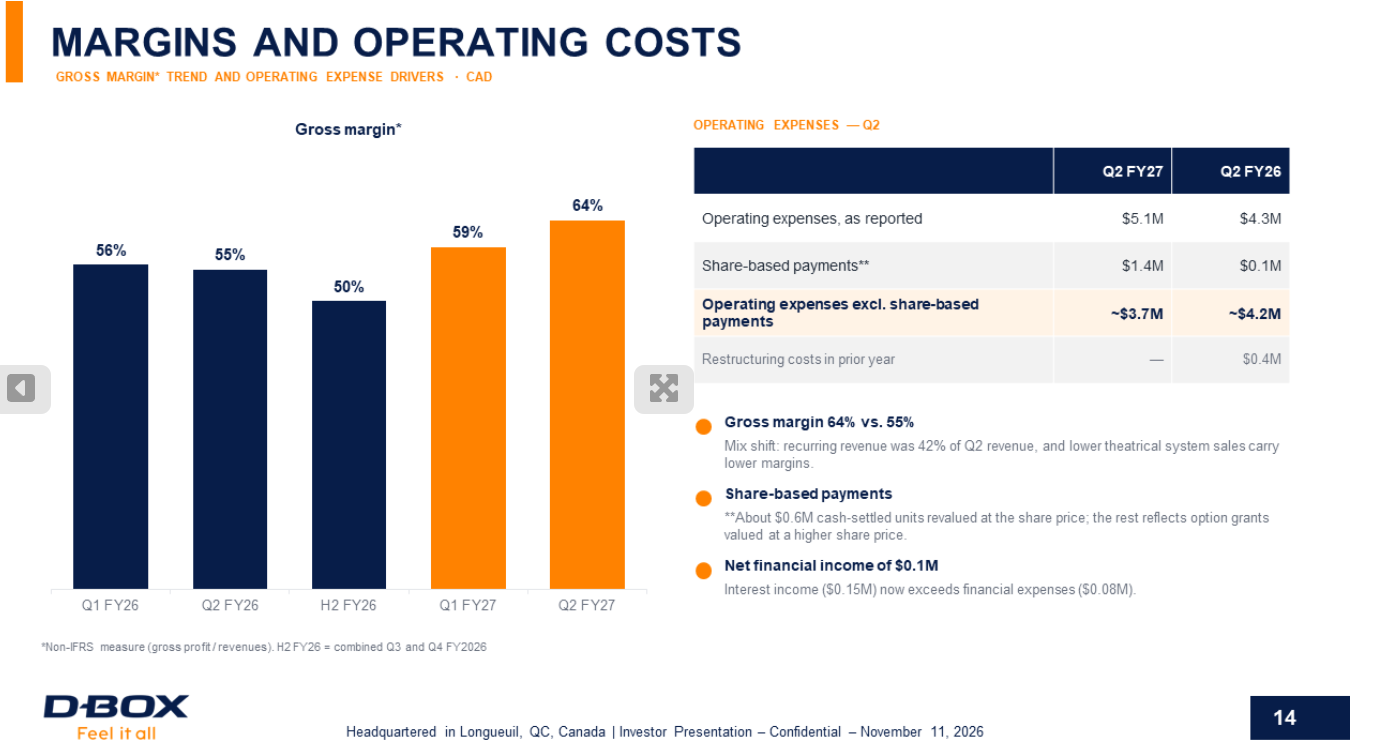
With SBC costs removed, the company indeed has delivered some decent operational leverage which many investors might miss on first glance. This also helps to explain the improved operational cash flow numbers.
There is some optimism in this quagmire of disappointment, but I will say that management doesn’t do the market any favours with not providing any type of guidance to the market - a weakness for any company that does earnings calls.
I also don’t like when management tries to piss on my head and tell me it’s raining with bullet point achievements of 42% of total revenues are now recurring. That’s bound to happen when two-thirds of your business shit the bed.
As I finish up here a half hour into the trading day, the stock decreased as much as 33% to $0.72. I added some at $0.75 and then flipped them at $0.90 which will help to lessen today’s overall pain.
Have to downgrade them here of course, but these are still 4 star FINS with improved cash flow and 22% profit margins.
Disclaimer:
My intent is for my reviews to be a bolt on to due diligence that you have already completed. I receive dozens of review requests a week, therefore my own DD may be great or none whatsoever. Unless otherwise stated or implied, my opinions are on the financial performance of the company based on their most recent filings. I conduct these reviews to assist other retail investors whose research skills are limited when it comes to reviewing financial statements. I do not accept compensation of any kind from company’s I review.
Wolf FINS Reviews are intended to be informational and are based on personal opinion. They are not intended to be financial advice, and all readers are encouraged to perform their own due diligence prior to their investment decisions, including discussions with their investment advisor.
My son, who is 25, disliked immensely the D-Box seats in the theaters, will not go to a movie again that has this technology installed.